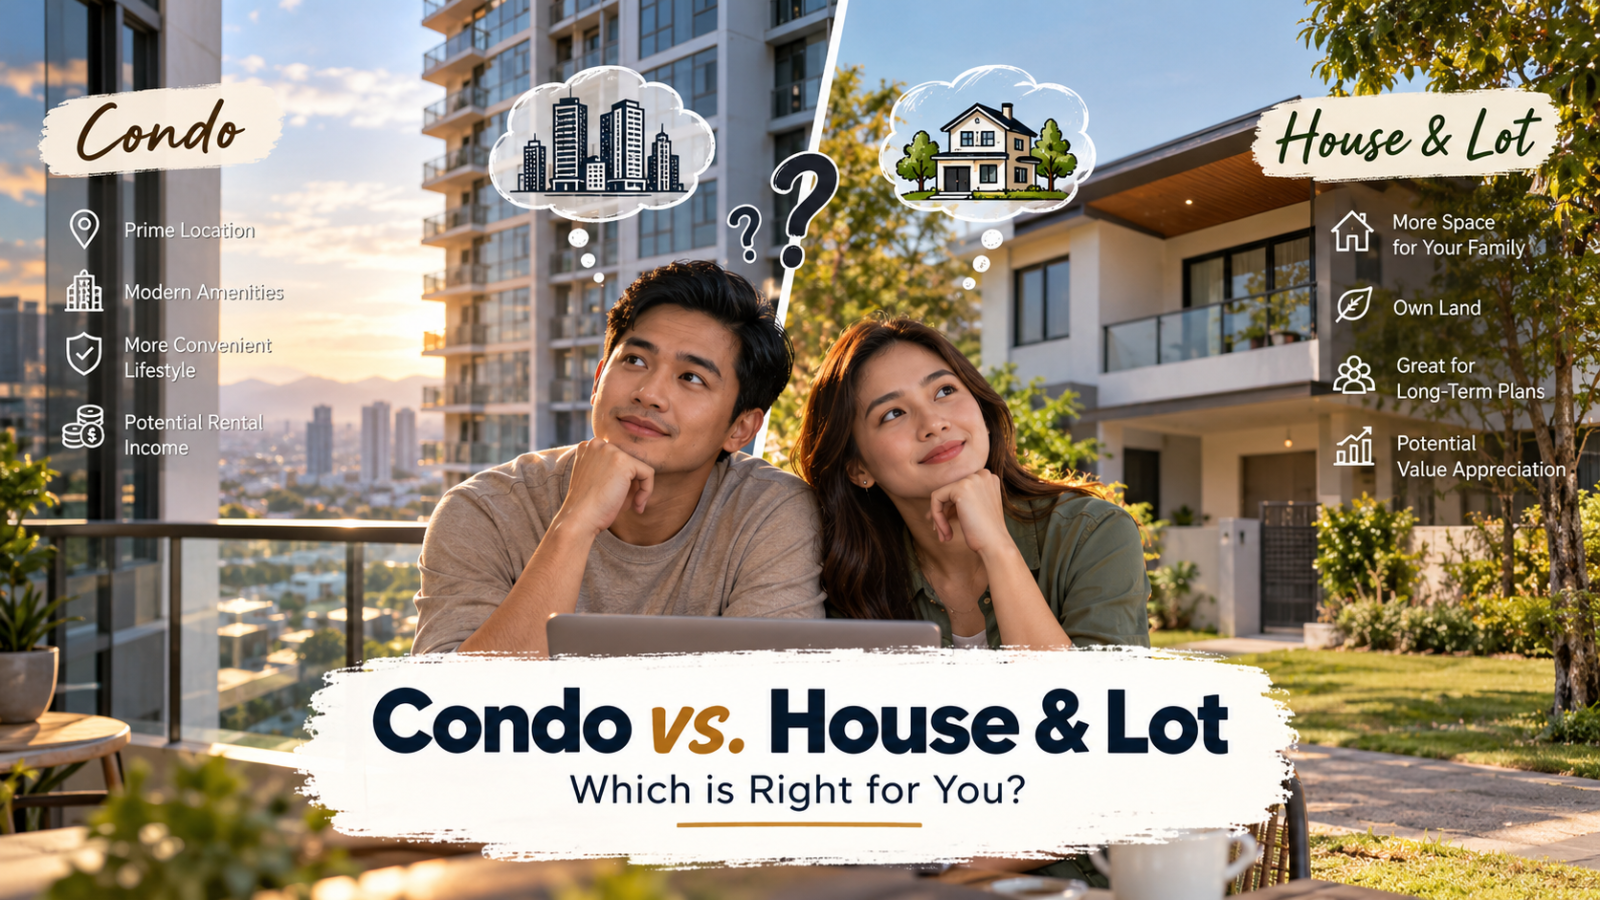
Choosing between a condo and a house and lot is one of the first big decisions most homebuyers in the Philippines face. Neither one is automatically the better buy. The right choice depends on how you live, where you work, how much you can pay every month, and what you want the property to be worth in ten or twenty years.
This guide is written for buyers in Davao, Cebu, Cagayan de Oro, and the rest of Mindanao and the Visayas. It covers the parts that sales brochures usually leave out.
THE QUICK COMPARISON
| Condo | House and Lot | |
|---|---|---|
| Total price | Usually lower ticket price | Usually higher ticket price |
| Price per square meter | Usually higher | Usually lower |
| Title | Condominium Certificate of Title (CCT) | Transfer Certificate of Title (TCT) |
| Monthly dues | Condo association dues, charged per square meter | HOA dues in most subdivisions, usually lower |
| Location | City centers and business districts | Often farther from the center at lower price points |
| Space | Smaller, no room to expand | Larger, room to renovate or extend |
| Maintenance | Common areas handled by building management | All repairs are yours |
| Foreign ownership | Allowed, up to 40% of units in a project | Foreigners cannot own the land |
| Long-term value | Driven by location and building upkeep | Land tends to appreciate even as the house ages |
Condo living
What works
- Location. Condos are built where land is expensive, which usually means near offices, malls, schools, and hospitals. If you work in a central business area, a condo can cut your daily commute significantly.
- Lower entry price. A studio or one-bedroom unit often costs less in total than a house in a comparable area, which makes it a common first property for young professionals.
- Security and amenities. Guards, CCTV, a pool, and a gym come with the building. For people who travel often, or OFWs buying for later, a locked-up unit is easier to leave alone than a house.
- Rental demand. Units near workplaces and universities are easier to rent out to professionals and students.
What to watch out for
- Association dues. These are charged per square meter, so a larger unit pays more. Ask for the current rate and how often it has gone up. Dues continue whether the unit is occupied or not.
- Price per square meter. The lower ticket price comes with a smaller space. Compare the cost per square meter, not just the total.
- Parking. Parking slots are usually sold separately, and in some buildings they are limited.
- Space for a growing family. You cannot add a room later. If you plan to have children or bring in parents, think about whether the unit will still fit in five years.
- Building quality over time. Your unit's value depends partly on how well the building is managed. Ask about the developer's track record with its older projects.
House and lot living
What works
- Space and flexibility. You get a yard, room for a car or two, and the option to renovate or build an extension, subject to subdivision rules and permits.
- Land value. The house depreciates as it ages, but the land under it generally appreciates. This is the main reason many Filipino families see a house and lot as a long-term investment.
- Privacy. No shared walls or hallways, and more freedom in how you use your space.
- Family fit. Better suited to children, pets, and multi-generational households.
What to watch out for
- HOA dues still apply. Most subdivisions charge homeowners association dues for security, road maintenance, and common areas. They are usually lower than condo dues, but they are not zero. Ask for the amount before you reserve.
- Distance. Affordable subdivisions are often on the edge of the city. Test the commute at rush hour, not on a Sunday afternoon.
- Repairs are all yours. Roofing, plumbing, termite treatment, and repainting add up over the years. Set aside a maintenance budget.
- Flooding and terrain. Some low-lying areas flood during heavy rain. Check the location on HazardHunterPH, ask residents, and visit after a rainy day if you can.
Things most guides leave out
Foreign ownership
Under the Condominium Act, foreigners may own condo units as long as foreign ownership in the project stays within 40%. Foreigners cannot own land, so a house and lot generally has to be titled to a Filipino citizen. This matters for OFWs married to foreign nationals and for families planning who will hold the title. Former natural-born Filipinos have limited rights to buy residential land, so get proper legal advice for your specific situation.
Financing
Both condos and house-and-lot properties can be financed through Pag-IBIG, bank loans, or in-house developer financing. Pag-IBIG usually offers the lowest rates and longest terms, but loan limits and requirements change, so check the current rules before you plan your budget. Bank loans generally need a stronger income profile. In-house financing is easier to qualify for but almost always costs more over the life of the loan.
Preselling vs. ready for occupancy
Preselling units cost less and let you spread your down payment over the construction period, but you wait for turnover and depend on the developer finishing on time. Ready-for-occupancy (RFO) units cost more but you can move in or rent out immediately. This choice applies to both condos and houses.
The real monthly cost
When you compare options, add up everything you will pay each month, not just the amortization:
- Loan amortization
- Association or HOA dues
- Parking, for condos
- Real property tax, spread across the year
- Utilities and a maintenance allowance
- Transport costs from that location
A cheaper house far from work can end up costing as much as a condo once fuel, fares, and time are counted.
Investment perspective
Condos in central areas tend to be easier to rent out and can earn steady rental income, especially near business districts, hospitals, and universities. Houses and lots in growing areas tend to gain more from land appreciation over the long term, but they are usually harder to rent out quickly and take longer to sell.
If you are buying mainly to rent out, look at a condo's location first. If you are buying to hold for many years, the land in a house and lot is often the stronger asset.
So which one is right for you?
A condo may fit you better if you are single or a young couple, you work in the city center, you travel often, you want a rental property, or you are a foreign national or buying with a foreign spouse.
A house and lot may fit you better if you have or are planning a family, you need space for parents or relatives, you own a car or two, you want to renovate over time, or you are thinking about long-term land value.
Start with the neighborhood. Where you will commute, where your children will go to school, and how the area handles a heavy rain will matter more day to day than the floor plan.
Still deciding? Browse our verified listings to compare condos and house-and-lot properties side by side, or schedule a site tour and see both options in person.