The Peso Hits ₱64 per Dollar: What It Means for OFWs and Philippine Real Estate
October 27, 2026 | HouselyPH | Real Estate & Market Insights
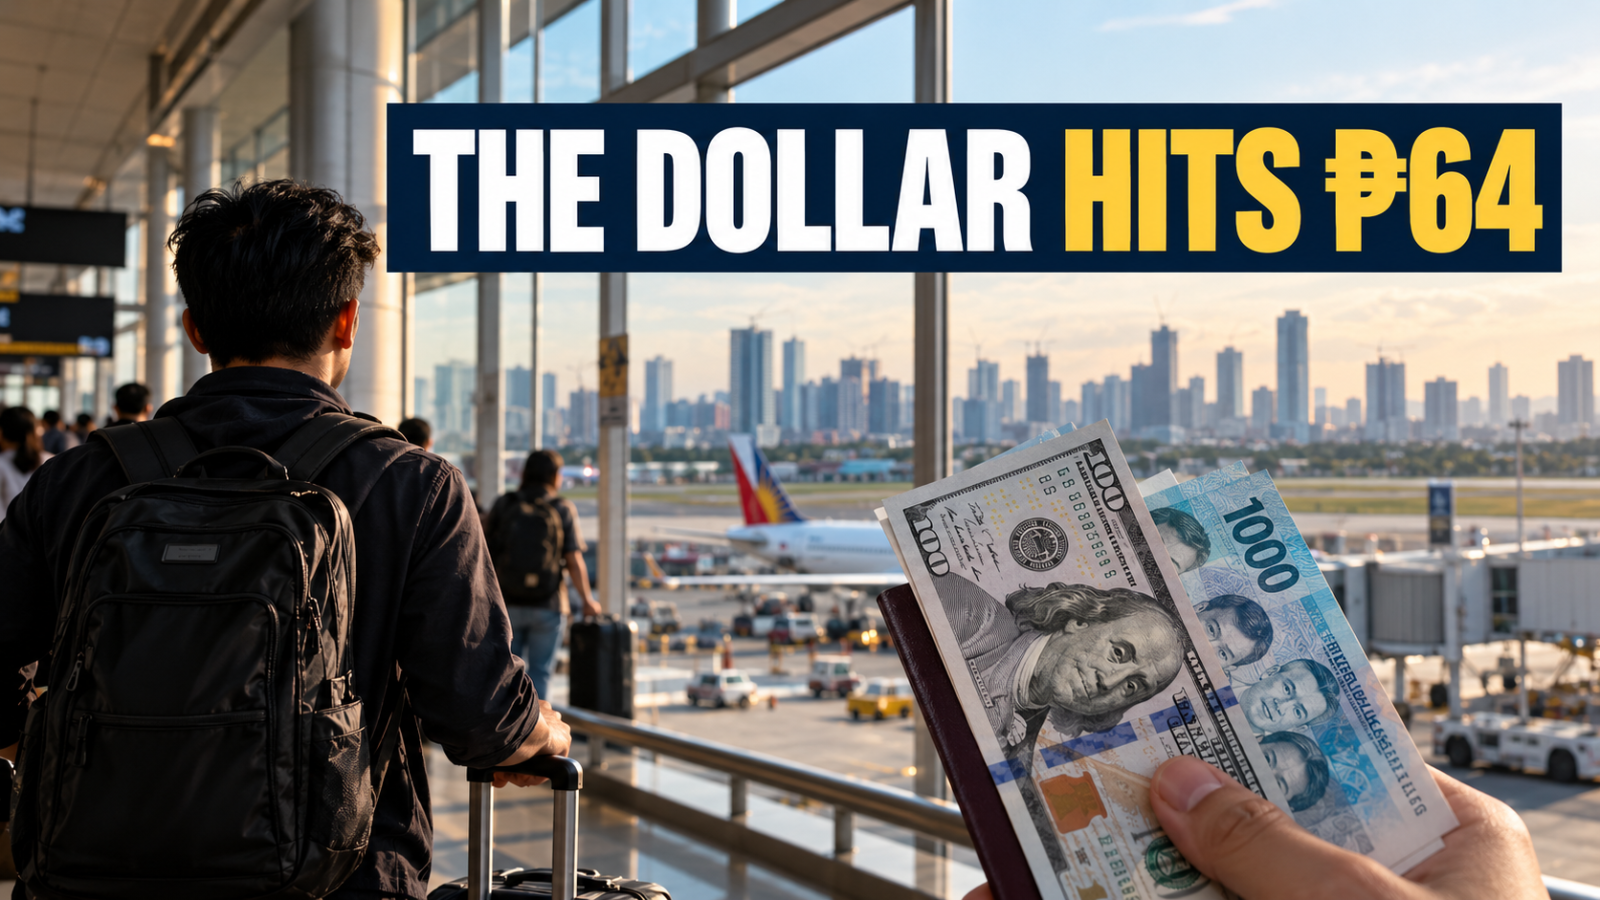
The Philippine peso has reached a significant milestone. On October 27, 2026, the peso touched ₱64 per US dollar during trading, following a record-low close of ₱63.95 the previous day.
For Overseas Filipino Workers (OFWs) earning in US dollars, this movement can mean more pesos for every dollar converted. But beyond the immediate benefit to family remittances, an important question arises: Could this also create an opportunity to invest in Philippine real estate?
The answer depends on your earning currency, financial commitments, investment goals, and the property you choose. A weaker peso may improve an OFW's purchasing power when buying peso-denominated property, but it does not automatically make every property a good investment.
Here is what OFWs need to know about the ₱64 milestone, their remittances, and investing in Philippine real estate.
What Does the Dollar Reaching ₱64 Mean?
When the US dollar strengthens against the Philippine peso, each dollar can be exchanged for more pesos. For OFWs earning in US dollars, this can increase the peso value of their remittances without requiring them to send more dollars.
For example, an OFW sending $1,000 could receive approximately ₱64,000 at an exchange rate of ₱64 per dollar, before transfer fees and differences between the market rate and the remittance provider's rate.
That additional peso value may help families cover household expenses, build savings, or prepare for long-term financial goals. However, exchange rates change constantly, and the peso may strengthen or weaken in the future.
It is also important to distinguish between an intraday exchange rate and a closing rate. The peso touching ₱64 during trading does not mean every bank or remittance provider will offer ₱64 for every dollar.
How the ₱64 Dollar-to-Peso Rate Affects OFWs
1. More pesos from dollar remittances
For OFWs earning in US dollars, a weaker peso can increase the peso value of the same remittance.
Consider the following illustration:
| Monthly Remittance | At ₱60/USD | At ₱64/USD | Difference |
|---|---|---|---|
| $500 | ₱30,000 | ₱32,000 | ₱2,000 |
| $1,000 | ₱60,000 | ₱64,000 | ₱4,000 |
| $2,000 | ₱120,000 | ₱128,000 | ₱8,000 |
| $3,000 | ₱180,000 | ₱192,000 | ₱12,000 |
Illustrative comparison only. ₱60 and ₱64 are example exchange rates, not a claim about the actual historical rate on a particular date. Actual remittance proceeds depend on the conversion rate and fees.
For a family receiving $1,000 monthly, the difference between these two example rates is ₱4,000. That could help with groceries, utilities, tuition, or savings.
However, higher living costs in the Philippines may reduce the benefit. The additional pesos do not automatically translate into greater purchasing power if household expenses are rising at the same time.
2. A chance to strengthen savings
When the exchange rate is favorable, OFWs may consider setting aside part of their additional peso value instead of increasing spending.
Depending on their financial circumstances, this could mean building an emergency fund, paying down expensive debt, preparing for children's education, or saving toward a future property purchase.
The key is to treat favorable exchange rates as a possible advantage, not a permanent source of extra income.
3. Not every OFW benefits equally
The US dollar is not the only currency earned by Filipinos working overseas. OFWs in the UAE, Saudi Arabia, Qatar, Singapore, Canada, Australia, and other countries earn in different currencies.
The impact on their purchasing power depends on how their own earning currency moves against the Philippine peso. They should check the exchange rate applicable to their salary and remittance provider rather than assuming that the USD/PHP rate tells the whole story.
Does a ₱64 Dollar Make Philippine Real Estate More Affordable?
For OFWs earning in US dollars, a weaker peso can reduce the dollar equivalent of a peso-denominated property payment.
For example, suppose an OFW has a remaining property equity obligation of ₱1,000,000.
| Exchange Rate | Dollar Equivalent |
|---|---|
| ₱60 per USD | Approximately $16,667 |
| ₱64 per USD | Approximately $15,625 |
At ₱64 per dollar, the same ₱1 million obligation would cost approximately $1,042 less than at ₱60 per dollar.
This does not mean the developer has reduced the property's price. The peso obligation remains ₱1 million; only its equivalent in US dollars changes.
If the peso strengthens again, future property payments may cost more in dollar terms. Buyers should therefore make sure they can afford their payment schedule even if exchange rates become less favorable.
Three Ways OFWs Can Invest in Philippine Real Estate
1. Buy a home for your family
For OFWs planning to return to the Philippines, buying a home may be an important long-term goal.
Instead of focusing only on the exchange rate, consider where your family wants to live, access to schools and hospitals, transportation, safety, and the total cost of ownership.
The right home is not necessarily the most expensive one. It is the property that meets your family's needs while remaining financially manageable throughout the payment period.
2. Consider a property with rental potential
Some OFWs explore condominiums and other residential properties as potential sources of rental income.
Properties near established business districts, universities, hospitals, and commercial centers may attract tenants. However, rental demand varies by location, property type, competing supply, price, and accessibility.
Before buying, evaluate realistic rental rates and account for association dues, maintenance, taxes, property management, vacancy periods, and other expenses. Rental income and property appreciation are not guaranteed.
3. Build an asset for retirement
For OFWs who eventually want to retire in the Philippines, a property may serve as a future home or a potential source of rental income.
However, real estate is less liquid than cash. Selling a property may take time, and its eventual selling price could be lower than expected.
Keep sufficient emergency savings outside your property investment and consider how long you intend to own the asset before making a purchase.
Should OFWs Buy Property Now or Wait?
Trying to predict the perfect exchange rate is difficult. The peso may weaken further, strengthen, or move in either direction as economic conditions change.
Waiting could result in a more favorable exchange rate, but it could also mean facing different property prices, financing costs, payment terms, or available units.
Rather than basing the decision on currency forecasts alone, consider these practical steps:
- Review your financial readiness. Maintain emergency savings and make sure your existing obligations leave room for property payments.
- Calculate the total acquisition cost. Include the reservation fee, equity schedule, applicable taxes and fees, financing costs, and ongoing ownership expenses.
- Stress-test your budget. Consider whether you could still afford the property if the peso strengthened against your earning currency.
- Research the location and developer. Evaluate accessibility, neighborhood conditions, documentation, delivery timelines, and comparable properties.
- Choose according to your goal. A family home, rental investment, and retirement property each have different requirements.
A sound property decision should remain manageable even if the exchange rate becomes less favorable. If the purchase only works when the dollar is strong, your budget may be too tight.
Why the Neighborhood Matters More Than the Exchange Rate Alone
A favorable exchange rate may help with the cost of purchasing property, but it cannot guarantee that a property will perform well as an investment.
Location, accessibility, employment opportunities, neighborhood development, rental demand, property condition, and overall value are all important considerations.
At HouselyPH, we believe that choosing a property starts with understanding the neighborhood before selecting the property itself.
For OFWs, that means looking beyond attractive payment terms and evaluating how a location fits their family plans, investment objectives, and financial capacity.
Whether you are exploring a condominium in Cebu, a residential development in Davao, or another property across the Visayas and Mindanao, start by understanding the area, the actual costs, and the long-term commitment involved.
The Bottom Line
The US dollar touching ₱64 per Philippine peso may offer OFWs earning in dollars greater peso purchasing power when converting their income. This can create an opportunity to strengthen savings, support family expenses, or manage peso-denominated property payments.
But a favorable exchange rate is only one part of the decision. Inflation, remittance fees, future currency movements, property expenses, and unexpected financial changes all deserve attention.
You do not need to predict the perfect exchange rate to make a sound property decision. You need a clear financial plan, a realistic budget, and a property that fits your long-term goals.
Working abroad and thinking about investing back home?
Let HouselyPH help you explore residential properties across the Philippines, compare neighborhoods, understand payment options, and identify properties that fit your budget and future plans.
Start with the neighborhood. Then find the property that makes sense for you.
Visit HouselyPH to explore your options or connect with our team for guidance on your next property decision.
Sources for exchange-rate verification:
- Bangko Sentral ng Pilipinas — Exchange Rate Statistics
- Metrobank Wealth Insights — Philippine market updates
Disclaimer: This article is for general educational purposes only and does not constitute financial, investment, tax, or legal advice. Exchange rates fluctuate, and the figures presented are illustrative. Property prices, rental income, appreciation, and investment returns are not guaranteed. Verify the latest exchange rates, property details, payment terms, and applicable costs before making a decision.